‘…if he should send an army against the Persians he would destroy a great empire.’: Herodotus, Histories, I.53

In the sixth century BC, Croesus, King of Lydia and, reportedly, the richest man alive, was considering war with the Persian Empire. Seeking guidance, he consulted the Oracle of Delphi. The answer appeared encouraging: any attack would result in the destruction of a great empire. Unfortunately for Croesus, while this information was correct, his interpretation was not. The empire that would ultimately fall was his own.

US Treasury Secretary Scott Bessent appears to be facing a similar problem.

Following recent US-Japanese intervention to support the yen, Bessent warned investors against taking the other side: “I have asymmetric information. I am the house now. You can bet against me if you want”. He subsequently commented that “if some of the Bloomberg terminal bros are unhappy with what I’m doing, well, that’s too bad.”

Like Croesus and the Oracle, Bessent’s confidence rests on privileged information. It is hard to dispute that advantage. Bessent almost certainly knows more than the market about what the US Treasury, Bank of Japan and Japanese government intend to do – but knowing what policymakers will do is not the same as knowing how markets will respond. This distinction is important when deciding whether such action can change market prices.

Recent Bank of America research provides a useful framework: intervention is most clearly justified where market failures, liquidity breakdowns or coordination problems are preventing efficient price discovery. The case for such action is also stronger when it is aligned with, rather than against, underlying fundamentals. The yen, for example, has a reasonable claim to being fundamentally cheap: purchasing power measures suggest substantial undervaluation and Japan continues to run a sizeable current account surplus, while interest rate differentials have narrowed. To date, therefore, such intervention appears to be reinforcing, rather than resisting, market fundamentals.

A harder case

The Treasury market looks rather different.

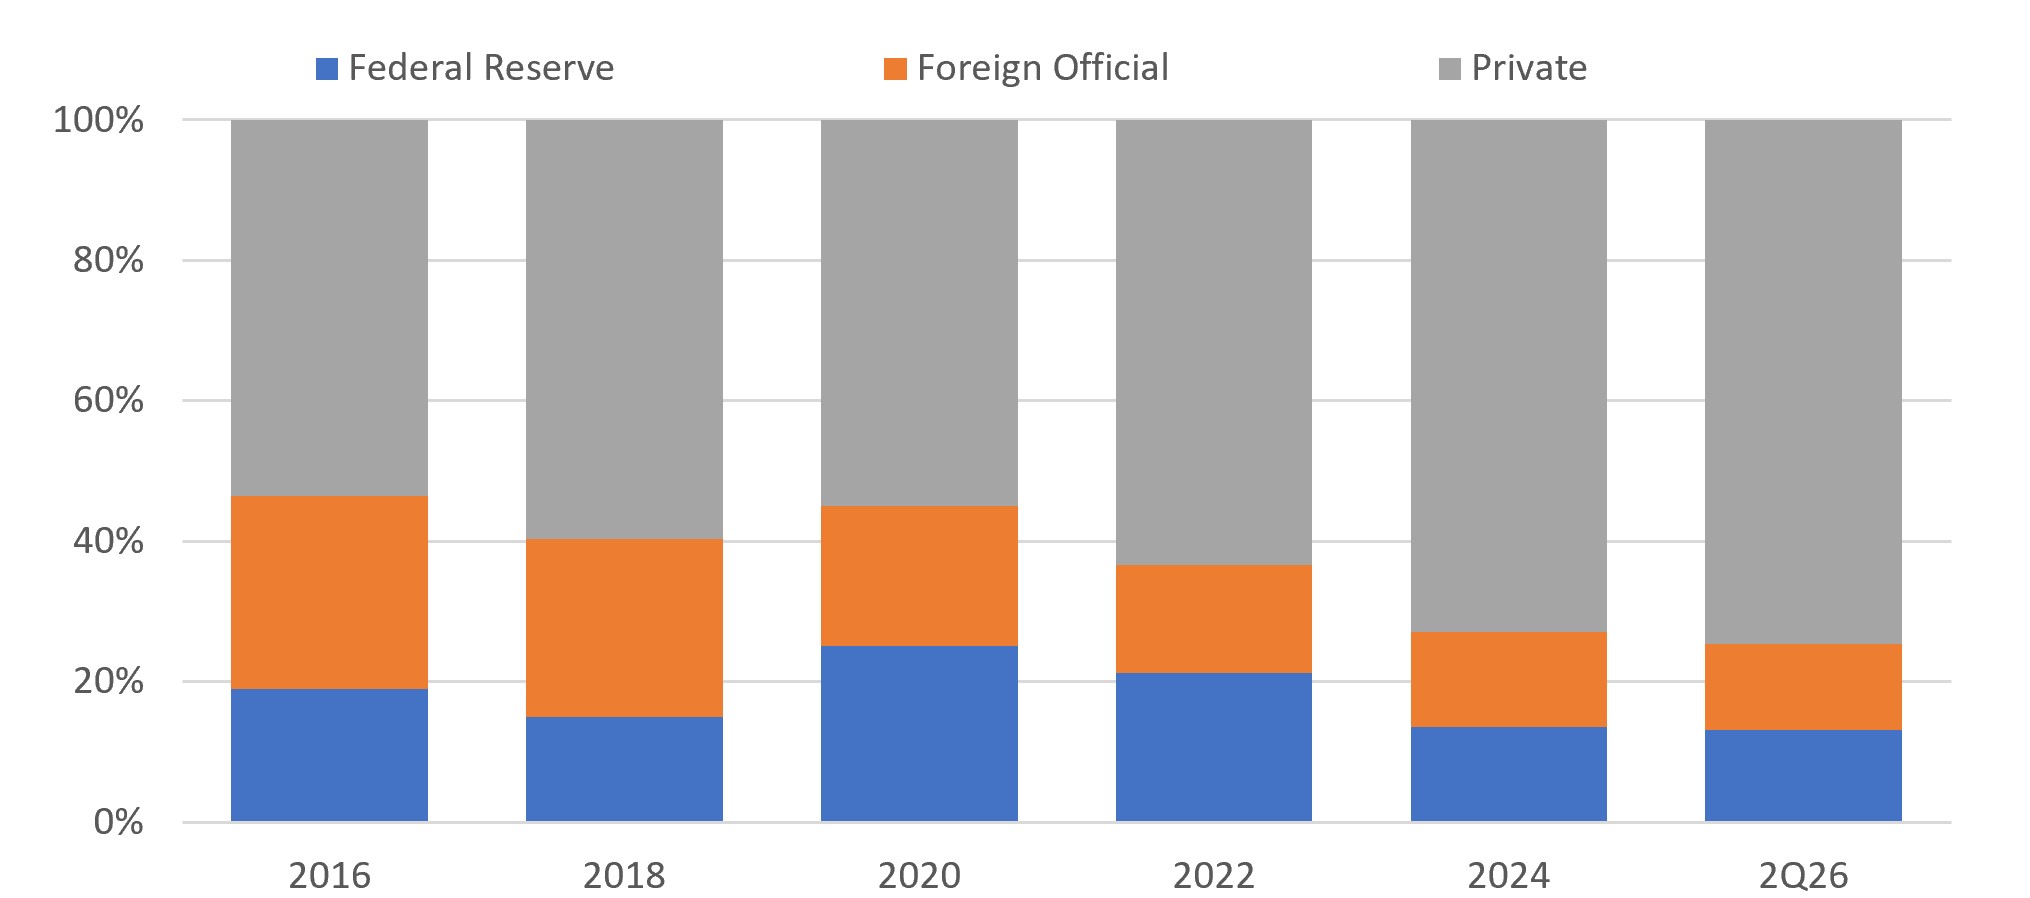
As we discussed in the Fund’s August commentary, the US is running a fiscal deficit of c6% of GDP. At the same time, Treasury ownership has shifted towards more price-sensitive investors, whose share has risen to roughly three-quarters today from just over half in 2016 (see the chart below). AI-related financing needs have also added to the competition for capital. As we highlighted in AI debt levels and the Eureka moment for credit markets, AI-related bond issuance alone had reached $380.5bn by mid-August.

Research from MIT in August estimates that the cost of absorbing additional US Treasury debt has more than doubled since 2015, from around 80bps to 187bps today. Higher long-term yields, therefore, appear not to represent market malfunction, but the greater compensation investors now require to hold government debt.

US Treasury ownership: An increasing reliance on private investors (1Q16 – 2Q26)

US Treasury ownership
Source: Polar Capital, Federal Reserve Financial Accounts, US Treasury International Capital System; September 2026.

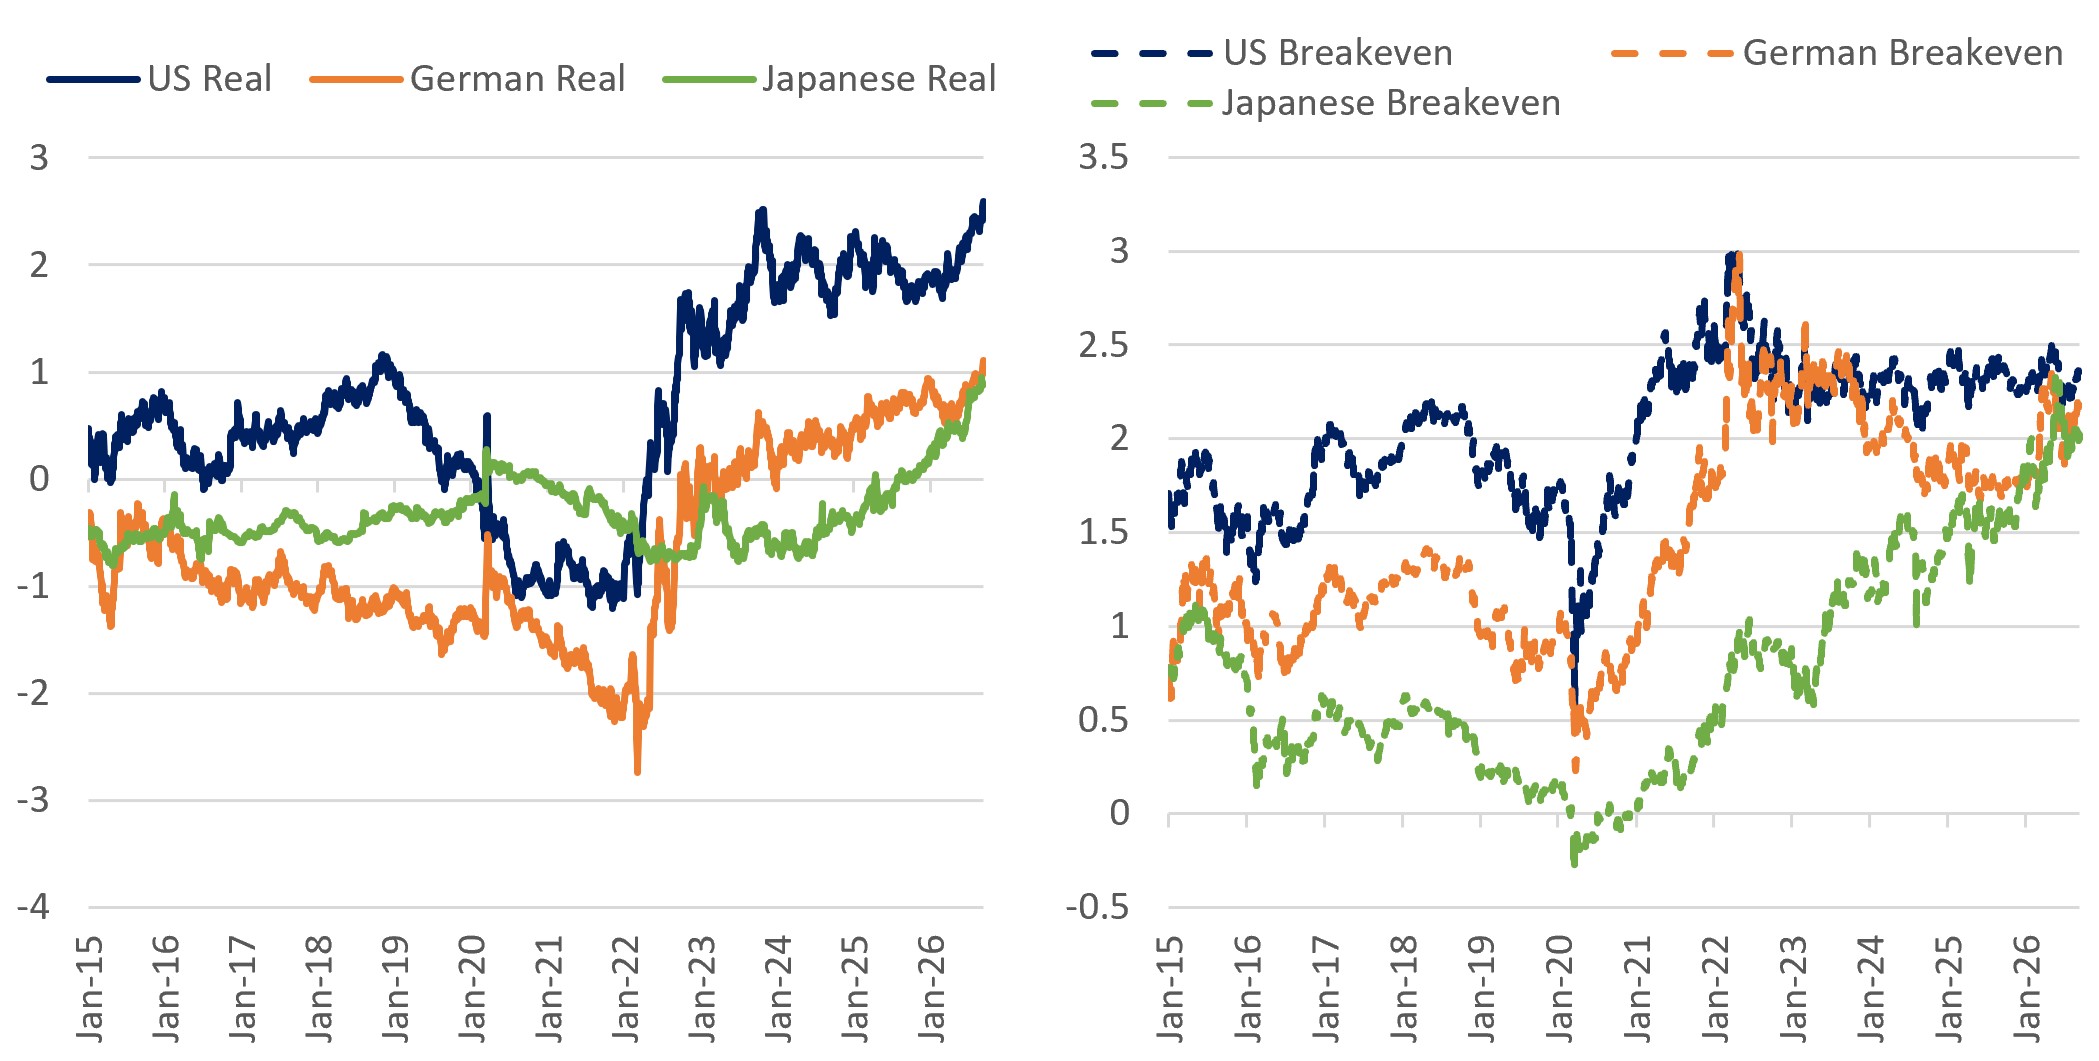
This is not solely a US phenomenon, with long-term government bond yields having risen across major developed markets, predominantly driven by higher real rates (see chart below).

Higher global yields driven by real rates: 10yr real rates & inflation breakevens (Jan 2015 – Sep 2026)

Higher global yields driven by real rates
Source: Polar Capital, Bloomberg; September 2026.

Bessent’s response

Bessent is increasingly seeking to manage that price. The US Treasury has expanded its long-dated bond buybacks, while changes have also been made to bank leverage rules and short-term issuance plans. Any future currency intervention is expected to use the Federal Reserve’s Foreign and International Monetary Authority (FIMA) repo facility, allowing foreign central banks to exchange Treasuries for dollars rather than sell them.

Such measures can influence near-term pricing by managing expectations, but if higher yields primarily reflect changed fundamentals rather than dysfunctional markets, intervention faces a more challenging task. Recent experience is instructive. The expansion of long-dated bond buybacks to $6bn, announced on 9 September, did not prevent yields from continuing to rise: the US 10-year Treasury hit its highest level since 2023, while the 30-year equivalent returned to the level seen before the August buyback announcement.

Bessent’s choice of language is particularly striking especially when set against how the political strategist James Carville once viewed the bond market. Carville famously said that, if reincarnated, he wanted to return as the bond market because “you can intimidate everybody”.

Conclusion

His interventions may ultimately prove successful, yet an informational advantage over policy intentions is not necessarily an informational advantage over market outcomes, particularly when the fundamentals underlying those markets have changed.

Croesus’s mistake was not that his information was wrong. It was believing it told him more than it did.
Risks

  • Capital is at risk and there is no guarantee the Fund will achieve its objective. Investors should make sure their attitude towards risk is aligned with the risk profile of the Fund before investing.
  • Past performance is not a reliable guide to future performance. The value of investments may go down as well as up and you might get back less than you originally invested as there is no guarantee in place.
  • The value of a fund’s assets may be affected by uncertainties such as international political developments, market sentiment, economic conditions, changes in government policies, restrictions on foreign investment and currency repatriation, currency fluctuations and other developments in the laws and regulations of countries in which investment may be made. Please see the Fund’s Prospectus for details of all risks.
  • The fund is exposed to Sustainability risks which are environmental, social and governance factors that could have an actual or potential material negative impact on the value of the Fund and its risk factors.
  • The Fund invests in fixed income securities, and prices can rise or fall due to several factors affecting global markets.
  • The Fund uses derivatives which carry the risk of reduced liquidity, substantial loss, and increased volatility in adverse market conditions, such as failure amongst market participants.
  • The Fund invests in assets denominated in currencies other than the Fund's base currency. Changes in exchange rates may have a negative impact on the Fund's investments. If the share class currency is different from the currency of the country in which you reside, exchange rate fluctuations may affect your returns when converted into your local currency. Hedged share classes may have associated costs which may impact the performance of your investment.
  • There may be times where the issuer or guarantor of a fixed income security cannot meet its payment obligations or has their credit rating downgraded, resulting in potential losses for the Fund.
  • The Fund may invest in emerging markets where there is a greater risk of volatility due to political and economic uncertainties, restrictions on foreign investment, currency repatriation and currency fluctuations. Developing markets are typically less liquid which may result in large price movements to the Fund.


Important Information:
This is a marketing communication and does not constitute a solicitation or offer to any person to buy or sell any related securities or financial instruments. Any opinions expressed may change. This document does not contain information material to the investment objectives or financial needs of the recipient. This document is not advice on legal, taxation or investment matters. Tax treatment depends on personal circumstances. Investors must rely on their own examination of the fund or seek advice. Investment may be restricted in other countries and as such, any individual who receives this document must make themselves aware of their respective jurisdiction and observe any restrictions.

A decision may be taken at any time to terminate the marketing of the Fund in any EEA Member State in which it is currently marketed. Shareholders in the affected EEA Member State will be given notification of any decision and provided the opportunity to redeem their interests in the Fund, free of any charges or deductions, for at least 30 working days from the date of the notification.

Investment in the Fund is an investment in the shares of the Fund and not in the underlying investments of the Fund. Further information about fund characteristics and any associated risks can be found in the Fund’s Key Information Document or Key Investor Information Document (“KID” or “KIID”), the Prospectus (and relevant Fund Supplement), the Articles of Association and the Annual and Semi-Annual Reports. Please refer to these documents before making any final investment decisions. These documents are available free of charge at Polar Capital Funds plc, Georges Court, 54-62 Townsend Street, Dublin 2, Ireland, via email by contacting Investor-Relations@polarcapitalfunds.com or at www.polarcapital.co.uk. The KID is available in the languages of all EEA member states in which the Fund is registered for sale; the Prospectus, Annual and Semi-Annual Reports and KIID are available in English.

The Fund promotes, among other characteristics, environmental or social characteristics and is classified as an Article 8 fund under the EU's Sustainable Finance Disclosure Regulation (SFDR). For more information, please see the Prospectus and relevant Fund Supplement.

ESG and sustainability characteristics are further detailed on the investment manager’s website: - https://www.polarcapital.co.uk/ESG-and-Sustainability/Responsible-Investing/.

A summary of investor rights associated with investment in the Fund can be found here.

This document is provided and approved by both Polar Capital LLP and Polar Capital (Europe) SAS.

Polar Capital LLP is authorised and regulated by the Financial Conduct Authority (“FCA”) in the United Kingdom, and the Securities and Exchange Commission (“SEC”) in the United States. Polar Capital LLP’s registered address is 16 Palace Street, London, SW1E 5JD, United Kingdom.

Polar Capital (Europe) SAS is authorised and regulated by the Autorité des marchés financiers (AMF) in France. Polar Capital (Europe) SAS’s registered address is 18 Rue de Londres, Paris 75009, France.

Polar Capital LLP is a registered Investment Advisor with the SEC. Polar Capital LLP is the investment manager and promoter of Polar Capital Funds plc – an open-ended investment company with variable capital and with segregated liability between its sub-funds – incorporated in Ireland, authorised by the Central Bank of Ireland and recognised by the FCA. FundRock Management Company (Ireland) Limited acts as management company and is regulated by the Central Bank of Ireland. Registered Address: Percy Exchange, 8/34 Percy Place, Dublin 4, Ireland.

For UK investors: The Fund is recognised in the UK under the Overseas Funds Regime (OFR) but it is not a UK-authorised Fund. UK investors should be aware that they may not be able to refer a complaint against its Management Company or its Depositary to the UK’s Financial Ombudsman Service. Any claims for losses relating to the Management Company or the Depositary will not be covered by the Financial Services Compensation Scheme, in the event that either entity should become unable to meet its liabilities to investors. For information on the complaint process to the Management Company, please see the Country Supplement for this fund available at https://www.polarcapital.co.uk/.

Benchmark: The Fund is actively managed and uses ICE BofA Global Financial Index as a reference for performance measurement. The benchmark has been chosen as it is generally considered to be representative of the investment universe in which the Fund invests. The performance of the Fund is likely to differ from the performance of the benchmark as the holdings, weightings and asset allocation will be different. Investors should carefully consider these differences when making comparisons. Further information about the benchmark can be found here. The benchmark is provided by an administrator on the European Securities and Markets Authority (ESMA) register of benchmarks which includes details of all authorised, registered, recognised, and endorsed EU and third country benchmark administrators together with their national competent authorities.

Third-party Data: Some information contained herein has been obtained from third party sources and has not been independently verified by Polar Capital. Neither Polar Capital nor any other party involved in or related to compiling, computing or creating the data makes any express or implied warranties or representations with respect to such data (or the results to be obtained by the use thereof), and all such parties hereby expressly disclaim all warranties of originality, accuracy, completeness, merchantability or fitness for a particular purpose with respect to any data contained herein.

Country Specific Disclaimers: Please be aware that not every share class of every fund is available in all jurisdictions. When considering an investment into the Fund, you should make yourself aware of the relevant financial, legal and tax implications. Neither Polar Capital LLP nor Polar Capital Funds plc shall be liable for, and accept no liability for, the use or misuse of this document.

None

‘…if he should send an army against the Persians he would destroy a great empire.’: Herodotus, Histories, I.53

In the sixth century BC, Croesus, King of Lydia and, reportedly, the richest man alive, was considering war with the Persian Empire. Seeking guidance, he consulted the Oracle of Delphi. The answer appeared encouraging: any attack would result in the destruction of a great empire. Unfortunately for Croesus, while this information was correct, his interpretation was not. The empire that would ultimately fall was his own.

US Treasury Secretary Scott Bessent appears to be facing a similar problem.

Following recent US-Japanese intervention to support the yen, Bessent warned investors against taking the other side: “I have asymmetric information. I am the house now. You can bet against me if you want”. He subsequently commented that “if some of the Bloomberg terminal bros are unhappy with what I’m doing, well, that’s too bad.”

Like Croesus and the Oracle, Bessent’s confidence rests on privileged information. It is hard to dispute that advantage. Bessent almost certainly knows more than the market about what the US Treasury, Bank of Japan and Japanese government intend to do – but knowing what policymakers will do is not the same as knowing how markets will respond. This distinction is important when deciding whether such action can change market prices.

Recent Bank of America research provides a useful framework: intervention is most clearly justified where market failures, liquidity breakdowns or coordination problems are preventing efficient price discovery. The case for such action is also stronger when it is aligned with, rather than against, underlying fundamentals. The yen, for example, has a reasonable claim to being fundamentally cheap: purchasing power measures suggest substantial undervaluation and Japan continues to run a sizeable current account surplus, while interest rate differentials have narrowed. To date, therefore, such intervention appears to be reinforcing, rather than resisting, market fundamentals.

A harder case

The Treasury market looks rather different.

As we discussed in the Fund’s August commentary, the US is running a fiscal deficit of c6% of GDP. At the same time, Treasury ownership has shifted towards more price-sensitive investors, whose share has risen to roughly three-quarters today from just over half in 2016 (see the chart below). AI-related financing needs have also added to the competition for capital. As we highlighted in AI debt levels and the Eureka moment for credit markets, AI-related bond issuance alone had reached $380.5bn by mid-August.

Research from MIT in August estimates that the cost of absorbing additional US Treasury debt has more than doubled since 2015, from around 80bps to 187bps today. Higher long-term yields, therefore, appear not to represent market malfunction, but the greater compensation investors now require to hold government debt.

US Treasury ownership: An increasing reliance on private investors (1Q16 – 2Q26)

US Treasury ownership
Source: Polar Capital, Federal Reserve Financial Accounts, US Treasury International Capital System; September 2026.

This is not solely a US phenomenon, with long-term government bond yields having risen across major developed markets, predominantly driven by higher real rates (see chart below).

Higher global yields driven by real rates: 10yr real rates & inflation breakevens (Jan 2015 – Sep 2026)

Higher global yields driven by real rates
Source: Polar Capital, Bloomberg; September 2026.

Bessent’s response

Bessent is increasingly seeking to manage that price. The US Treasury has expanded its long-dated bond buybacks, while changes have also been made to bank leverage rules and short-term issuance plans. Any future currency intervention is expected to use the Federal Reserve’s Foreign and International Monetary Authority (FIMA) repo facility, allowing foreign central banks to exchange Treasuries for dollars rather than sell them.

Such measures can influence near-term pricing by managing expectations, but if higher yields primarily reflect changed fundamentals rather than dysfunctional markets, intervention faces a more challenging task. Recent experience is instructive. The expansion of long-dated bond buybacks to $6bn, announced on 9 September, did not prevent yields from continuing to rise: the US 10-year Treasury hit its highest level since 2023, while the 30-year equivalent returned to the level seen before the August buyback announcement.

Bessent’s choice of language is particularly striking especially when set against how the political strategist James Carville once viewed the bond market. Carville famously said that, if reincarnated, he wanted to return as the bond market because “you can intimidate everybody”.

Conclusion

His interventions may ultimately prove successful, yet an informational advantage over policy intentions is not necessarily an informational advantage over market outcomes, particularly when the fundamentals underlying those markets have changed.

Croesus’s mistake was not that his information was wrong. It was believing it told him more than it did.

Related Fund

Get the latest insights sent straight to your inbox

Risks

  • Capital is at risk and there is no guarantee the Fund will achieve its objective. Investors should make sure their attitude towards risk is aligned with the risk profile of the Fund before investing.
  • Past performance is not a reliable guide to future performance. The value of investments may go down as well as up and you might get back less than you originally invested as there is no guarantee in place.
  • The value of a fund’s assets may be affected by uncertainties such as international political developments, market sentiment, economic conditions, changes in government policies, restrictions on foreign investment and currency repatriation, currency fluctuations and other developments in the laws and regulations of countries in which investment may be made. Please see the Fund’s Prospectus for details of all risks.
  • The fund is exposed to Sustainability risks which are environmental, social and governance factors that could have an actual or potential material negative impact on the value of the Fund and its risk factors.
  • The Fund invests in fixed income securities, and prices can rise or fall due to several factors affecting global markets.
  • The Fund uses derivatives which carry the risk of reduced liquidity, substantial loss, and increased volatility in adverse market conditions, such as failure amongst market participants.
  • The Fund invests in assets denominated in currencies other than the Fund's base currency. Changes in exchange rates may have a negative impact on the Fund's investments. If the share class currency is different from the currency of the country in which you reside, exchange rate fluctuations may affect your returns when converted into your local currency. Hedged share classes may have associated costs which may impact the performance of your investment.
  • There may be times where the issuer or guarantor of a fixed income security cannot meet its payment obligations or has their credit rating downgraded, resulting in potential losses for the Fund.
  • The Fund may invest in emerging markets where there is a greater risk of volatility due to political and economic uncertainties, restrictions on foreign investment, currency repatriation and currency fluctuations. Developing markets are typically less liquid which may result in large price movements to the Fund.


Important Information:
This is a marketing communication and does not constitute a solicitation or offer to any person to buy or sell any related securities or financial instruments. Any opinions expressed may change. This document does not contain information material to the investment objectives or financial needs of the recipient. This document is not advice on legal, taxation or investment matters. Tax treatment depends on personal circumstances. Investors must rely on their own examination of the fund or seek advice. Investment may be restricted in other countries and as such, any individual who receives this document must make themselves aware of their respective jurisdiction and observe any restrictions.

A decision may be taken at any time to terminate the marketing of the Fund in any EEA Member State in which it is currently marketed. Shareholders in the affected EEA Member State will be given notification of any decision and provided the opportunity to redeem their interests in the Fund, free of any charges or deductions, for at least 30 working days from the date of the notification.

Investment in the Fund is an investment in the shares of the Fund and not in the underlying investments of the Fund. Further information about fund characteristics and any associated risks can be found in the Fund’s Key Information Document or Key Investor Information Document (“KID” or “KIID”), the Prospectus (and relevant Fund Supplement), the Articles of Association and the Annual and Semi-Annual Reports. Please refer to these documents before making any final investment decisions. These documents are available free of charge at Polar Capital Funds plc, Georges Court, 54-62 Townsend Street, Dublin 2, Ireland, via email by contacting Investor-Relations@polarcapitalfunds.com or at www.polarcapital.co.uk. The KID is available in the languages of all EEA member states in which the Fund is registered for sale; the Prospectus, Annual and Semi-Annual Reports and KIID are available in English.

The Fund promotes, among other characteristics, environmental or social characteristics and is classified as an Article 8 fund under the EU's Sustainable Finance Disclosure Regulation (SFDR). For more information, please see the Prospectus and relevant Fund Supplement.

ESG and sustainability characteristics are further detailed on the investment manager’s website: - https://www.polarcapital.co.uk/ESG-and-Sustainability/Responsible-Investing/.

A summary of investor rights associated with investment in the Fund can be found here.

This document is provided and approved by both Polar Capital LLP and Polar Capital (Europe) SAS.

Polar Capital LLP is authorised and regulated by the Financial Conduct Authority (“FCA”) in the United Kingdom, and the Securities and Exchange Commission (“SEC”) in the United States. Polar Capital LLP’s registered address is 16 Palace Street, London, SW1E 5JD, United Kingdom.

Polar Capital (Europe) SAS is authorised and regulated by the Autorité des marchés financiers (AMF) in France. Polar Capital (Europe) SAS’s registered address is 18 Rue de Londres, Paris 75009, France.

Polar Capital LLP is a registered Investment Advisor with the SEC. Polar Capital LLP is the investment manager and promoter of Polar Capital Funds plc – an open-ended investment company with variable capital and with segregated liability between its sub-funds – incorporated in Ireland, authorised by the Central Bank of Ireland and recognised by the FCA. FundRock Management Company (Ireland) Limited acts as management company and is regulated by the Central Bank of Ireland. Registered Address: Percy Exchange, 8/34 Percy Place, Dublin 4, Ireland.

For UK investors: The Fund is recognised in the UK under the Overseas Funds Regime (OFR) but it is not a UK-authorised Fund. UK investors should be aware that they may not be able to refer a complaint against its Management Company or its Depositary to the UK’s Financial Ombudsman Service. Any claims for losses relating to the Management Company or the Depositary will not be covered by the Financial Services Compensation Scheme, in the event that either entity should become unable to meet its liabilities to investors. For information on the complaint process to the Management Company, please see the Country Supplement for this fund available at https://www.polarcapital.co.uk/.

Benchmark: The Fund is actively managed and uses ICE BofA Global Financial Index as a reference for performance measurement. The benchmark has been chosen as it is generally considered to be representative of the investment universe in which the Fund invests. The performance of the Fund is likely to differ from the performance of the benchmark as the holdings, weightings and asset allocation will be different. Investors should carefully consider these differences when making comparisons. Further information about the benchmark can be found here. The benchmark is provided by an administrator on the European Securities and Markets Authority (ESMA) register of benchmarks which includes details of all authorised, registered, recognised, and endorsed EU and third country benchmark administrators together with their national competent authorities.

Third-party Data: Some information contained herein has been obtained from third party sources and has not been independently verified by Polar Capital. Neither Polar Capital nor any other party involved in or related to compiling, computing or creating the data makes any express or implied warranties or representations with respect to such data (or the results to be obtained by the use thereof), and all such parties hereby expressly disclaim all warranties of originality, accuracy, completeness, merchantability or fitness for a particular purpose with respect to any data contained herein.

Country Specific Disclaimers: Please be aware that not every share class of every fund is available in all jurisdictions. When considering an investment into the Fund, you should make yourself aware of the relevant financial, legal and tax implications. Neither Polar Capital LLP nor Polar Capital Funds plc shall be liable for, and accept no liability for, the use or misuse of this document.